
Key Takeaways
Large strategic asset trades returned to the Appalachian Basin. Antero Resources' $2.8 billion acquisition of HG Energy II's West Virginia Marcellus assets and $800 million sale of its Ohio Utica upstream position accounted for most of the disclosed transaction value during the review period.
Reported valuation metrics varied widely. Disclosed benchmarks ranged from 3.7x to 8.0x projected EBITDAX or EBITDA, while a smaller royalty sale was priced at 6.0x expected next-12-month cash flow. Differences in operatorship, production mix, inventory, contractual rights, and strategic fit limit direct comparisons.
The buyer universe continued to broaden. U.S. producers and mineral aggregators remained active, while POSCO International added international strategic capital and Alpha Compute linked upstream and real estate acquisitions to a natural gas-powered data center strategy
Overview
Merger and acquisition activity in the Appalachian Basin was selective from October 2025 through September 2026, but the market was more varied than the prior period's emphasis on smaller bolt-ons and structured capital programs. The disclosed transactions ranged from a $3.9 million sale of overriding royalty interests to Antero Resources' $2.8 billion acquisition of a large West Virginia Marcellus position from HG Energy II. The review period also included a $550 million non-operated Marcellus acquisition by an international buyer, a multi-basin mineral acquisition program, and two transactions involving a buyer pursuing natural gas-powered data center development in Pennsylvania.
The mix matters as much as the headline values. The period did not produce a broad consolidation wave across the Marcellus and Utica. Instead, activity concentrated around assets that offered scale, strategic alignment, existing production, or a specialized ownership position. The transactions also illustrate why Appalachian valuation benchmarks require careful interpretation. The observed transactions span different ownership rights and asset profiles, including operated, non-operated working interests, overriding royalty interests, and packages combining mineral, surface, and infrastructure-related assets. Their economics also vary based on existing production, undeveloped inventory, development obligations, operating control, and the specific rights conveyed.
Transaction Activity
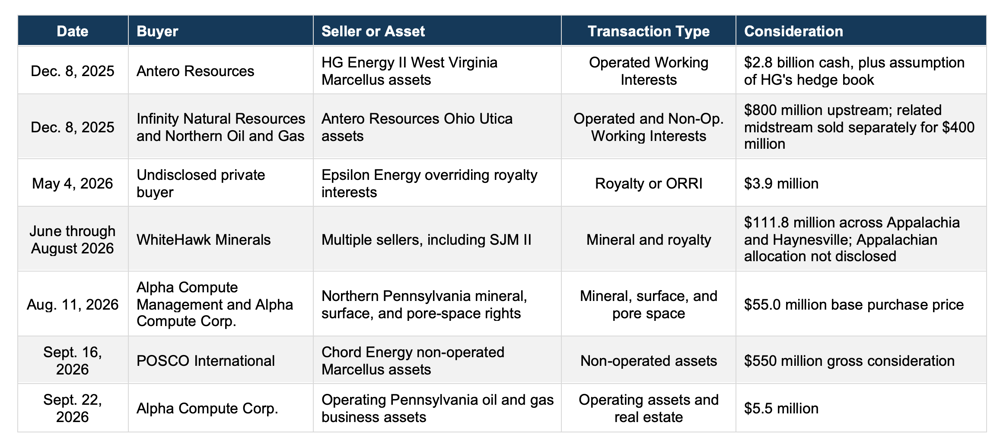
The following table summarizes the transactions identified during the review period.The more notable transactions are discussed in more detail below.
Antero Resources and HG Energy II
On December 8, 2025, Antero Resources announced an agreement to acquire HG Energy II's West Virginia Marcellus upstream assets for $2.8 billion in cash, plus the assumption of HG's hedge book. The assets were expected to add approximately 850 MMcfe per day of 2026 production, 385,000 net acres, and more than 400 gross drilling locations with an average lateral length of approximately 20,300 feet.
Antero cited a purchase price equal to approximately 3.7x projected 2026 EBITDAX, an expected 2026 free cash flow yield above 18%, and approximately $950 million of PV-10 synergies over ten years. Those disclosures show that Antero's acquisition case depended on more than current production. The large acreage position, long-lateral inventory, hedge book, and expected operating synergies were all components of the announced economics.
Antero Resources Ohio Utica Divestiture
As part of the same strategic repositioning, Antero agreed to sell its Ohio Utica upstream assets to Infinity Natural Resources and Northern Oil and Gas for $800 million in cash. The related midstream assets were sold separately for $400 million. Antero reported expected 2026 production of approximately 150 MMcfe per day for the upstream assets and an implied valuation of approximately 8.0x projected 2026 EBITDAX, with a projected 2026 free cash flow yield of approximately 7%.
Northern Oil and Gas acquired a 40% interest in the combined upstream and midstream package for $480 million. The interest was reduced from NOG's originally announced 49% interest for $588 million on the same pro rata terms as part of the pending joint acquisition with Infinity. Of NOG's consideration, 67% was allocated to upstream assets and 33% to midstream assets. Its 40% share included approximately 29,000 net acres, expected 2026 production of 53 MMcfe per day, and more than 100 gross undeveloped locations. The paired acquisition and divestiture allowed Antero to add a larger West Virginia Marcellus position while monetizing its Ohio Utica assets, and it provides two distinctly different transaction benchmarks announced on the same day.
WhiteHawk Minerals Acquisition Program
From June through August 2026, WhiteHawk Minerals entered into nine mineral and royalty acquisitions with aggregate consideration of $111.8 million. The acquired interests covered the Marcellus, Utica, and Haynesville, and the transaction disclosure indicated that most of the purchase price related to SJM II's Marcellus and Utica assets. An Appalachian-only allocation was not disclosed.
Across the combined acquisition program, the interests included more than 1,700 producing wells, 160 wells in process, 85 permitted locations, and 2,500 undeveloped locations. Expected production was approximately 16 MMcfe per day in 2027 and 17 MMcfe per day in 2028. Because the disclosed consideration and operating statistics include Haynesville assets, the $111.8 million aggregate value should not be treated as a stand-alone Appalachian transaction benchmark. The program nevertheless demonstrates continued demand for diversified mineral and royalty exposure to long-lived natural gas development.
POSCO International and Chord Energy
On September 16, 2026, Chord Energy announced an agreement to sell its non-operated Marcellus position in northeast Pennsylvania to POSCO International for gross consideration of $550 million. The assets included approximately 32,000 net acres and trailing-12-month production of approximately 121 MMcf per day. Production was entirely residue gas, with no natural gas liquids.
Chord reported a transaction value of approximately 6.0x adjusted EBITDA using a $3.50 per MMBtu Henry Hub price assumption. The acquisition is notable for both the buyer and the ownership structure. POSCO added direct exposure to U.S. natural gas through a non-operated interest, obtaining existing production and development potential without assuming operatorship. The transaction also shows that large Appalachian gas positions continue to attract international strategic capital.
Outlook
The transactions announced through September 2026 point to a market that can support large Appalachian deals when assets offer meaningful scale and a clear strategic fit. At the same time, most of the identified activity occurred outside a traditional whole-company consolidation. Non-operated interests, minerals and royalties, and integrated asset packages gave buyers several ways to obtain natural gas exposure while tailoring capital requirements and operating risk.
Future activity is likely to remain selective. Portfolio repositioning by established producers could create additional opportunities, while international buyers may continue to seek direct U.S. gas exposure. Growing interest in gas-fired power for data centers may also expand the buyer universe for assets that combine resource ownership with surface access and infrastructure. Valuations will remain sensitive to commodity price assumptions, takeaway access, drilling inventory, development timing, operatorship, and the precise legal and economic rights conveyed.
Conclusion
Appalachian Basin M&A from October 2025 through September 2026 was defined by one large strategic repositioning and a diverse group of smaller transactions. The period showed continued demand for high-quality Marcellus and Utica assets, but buyers pursued that exposure through several structures rather than a single consolidation model. For valuation purposes, the observed prices and multiples are useful reference points only after accounting for differences in asset quality, ownership rights, development obligations, and strategic fit.
Mercer Capital has assisted clients with valuation needs in the upstream oil and gas industry for conventional and unconventional plays in North America and around the world. Contact a Mercer Capital professional to discuss your needs in confidence.