Transaction Advisory, Investment Management

September 28, 2015

Look out below! As capital market valuations apex, so too will RIA margins

Investment returns and the steady upward drift of equity markets are usually kind to investment management firm profits and valuations.This does not seem to be a “usual” period, however, and it serves as a reminder that profit margins are not simply an allocation of returns to equity holders; they also serve as a margin of safety in bear markets.

Few industries are as susceptible to market conditions as the typical RIA.With revenues directly tied to stock indexes (in the case of equity managers) and a relatively high percentage of fixed costs, industry margins tend to sway with market variations.While the concept of operating leverage is not new to anyone in the asset management industry, it is easy to forget how easy it is for margins to collapse in a market downturn.
Mercer-Capital_Asset-Manager-Margins-SPjpg

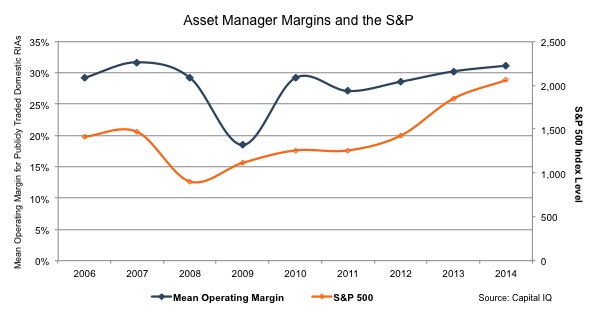
It is, of course, striking to notice how RIA margins have recovered to the previous peak of 2007, a potentially ominous warning for equity markets now.Even more striking is how deep profits can fall in a market meltdown.

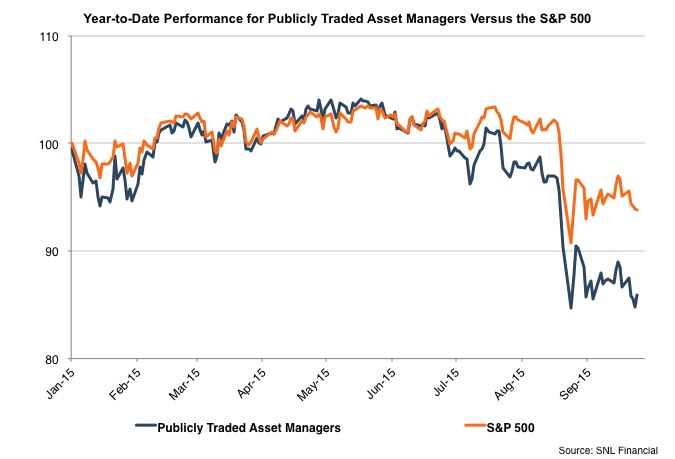
The Qs reflecting the P&L impact from the most recent correction aren’t out yet, but we suspect that profits will be adversely affected for at least the next couple of quarters, depending on the extent of the downturn.Indeed, the market appears to be already anticipating this for most publicly traded asset managers, as they have lost several billion dollars in aggregate market cap over the last six weeks.
Mercer-Capital_YTD-Perf-Publicly-Traded-AM-SP

On the private end of the spectrum, smaller, closely held RIAs tend to be more susceptible to market conditions than their publicly traded counterparts.Private RIAs don’t typically have the AUM and corresponding profit margins to serve as a cushion against a bear market.Anecdotally, we saw many asset managers with under $1 billion in AUM report negative earnings in 2008 and 2009 (at least for a few quarters) while most of the public RIAs stayed in the black.A healthy, larger RIA with 30% to 40% margins in good times can absorb a bear market event without reporting a loss, but many closely held asset managers with half that margin aren’t so resilient.

The upward drift in the market from 2009 to 2014 buoyed AUM levels to new highs without the corresponding increase in expenses for many asset managers whose only variable costs tend to be compensation related.As a result, our group of publicly traded asset managers was able to recoup their entire 11% drop in average profit margins in just one year after the financial crisis. Only a few years after 2009, asset manager margins swelled to unprecedented levels; but operating leverage works both ways, and many public RIAs are trading in bear market territory following last month’s correction.The recent downturn should serve as a wake-up call to an industry that hasn’t had much interference in its upward trajectory over the last several years.

As valuations drop and revenues contract, more attention must be devoted to expense controls if margins are to be maintained in the short run.Moving forward, this may be a challenge for many industry participants facing higher regulatory costs, a growing complexity of financial products, and personnel expenses that have moved almost in lockstep with revenue since the credit crisis.All of these costs tend to be fairly sticky on the downside.
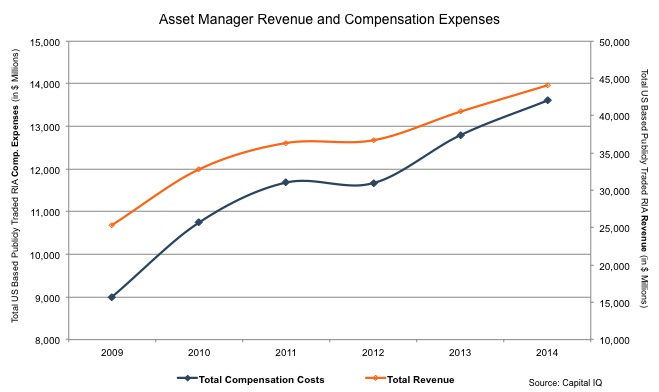
Mercer-Capital_Asset-Manager-Revenue-Compensation-Expenses Against a backdrop of increasing fee pressure and robo-advisory competition, this correction may have been long overdue for an industry that’s nearly doubled in size since the Great Recession. Though future market performance remains uncertain, it’s hard to imagine that RIA margin expansion will continue its ascent from the prior six years without another bull market tailwind.

Mercer Capital's RIA Valuation Insights Blog

The RIA Valuation Insights Blog presents a weekly update on issues important to the Asset Management Industry.

Continue Reading

When RIA Owners Disagree on Value

Choosing the Appraiser, the Process, and the Rules of Engagement

Valuation disputes among RIA owners require more than a defensible appraisal—they also require a clear process for selecting a qualified, independent appraiser and establishing fair rules of engagement. Thoughtful dispute-resolution provisions can help parties reach a credible conclusion even when perspectives on value differ.
RIA Valuation Insights Blog Investment Management
Read Now about When RIA Owners Disagree on Value
Mercer Capital to Sponsor the Association of Trust Organizations 2026 Annual Meeting
Mercer Capital is pleased to sponsor the Association of Trust Organizations’ 2026 Annual Meeting, taking place September 21-23, 2026, at the Grand Hyatt Deer Valley in Park City, Utah. Matt Crow, Brooks Hamner, and Zach Milam will attend on behalf of the firm.The 2026 Annual Meeting is a 1.5-day conference designed exclusively for the trust industry and will feature more than 13 hours of roundtables, panels, and networking. One of the featured sessions is Tuesday afternoon’s Session VI, “What Makes a Trust Company Worth More? Building Value Before the Deal,” which will be moderated by Matt Crow. The panel will explore the factors that drive valuation, how buyers and sellers evaluate opportunities, and what firms can do today to maximize enterprise value.Matt Crow, CFA, ASA, is the CEO of Mercer Capital and leads the firm’s Investment Management Industry team. He works with RIAs, independent trust companies, broker-dealers, and investment consulting firms on valuation matters related to corporate planning and reorganization, transactions, employee stock ownership plans, tax issues, and intangible asset valuations. Matt is also a frequent contributor to Mercer Capital’s RIA Valuation Insights blog.Brooks Hamner, CFA, ASA, is a Senior Vice President and a senior member of Mercer Capital’s Investment Management Industry team. He provides valuation services to RIAs, independent trust companies, asset managers, wealth management firms, broker-dealers, and investment consultants, and he also advises clients buying or selling their business.Zach Milam, CFA, is a Vice President and a senior member of Mercer Capital’s Investment Management Industry team. He has experience in corporate planning and reorganizations, financial reporting, fairness opinions, litigation support, employee stock ownership plans, and estate and gift tax planning and compliance matters.Mercer Capital regularly works with RIAs, independent trust companies, broker-dealers, and other investment management clients on valuation and advisory matters, and the firm looks forward to connecting with attendees in Park City. Visit the conference website to learn more about this year’s Annual Meeting: https://trustorgs.com/annual-meeting/.
The Margin RIA Buyers Actually Underwrite

Why the Post-Closing Cost Structure Matters More Than the Historical Margin

RIA buyers often focus less on a seller’s historical margin than on the earnings the business can generate after closing under the buyer’s operating model. Differences in integration strategy, cost structure, and platform capabilities can lead buyers to underwrite materially different margins and values.
RIA Valuation Insights Blog Investment Management
Read Now about The Margin RIA Buyers Actually Underwrite

Cart

Your cart is empty