Transaction Advisory, Investment Management

January 6, 2020

All Classes of Investment Management Firms Outperformed the Market in Q4

2019 Was Also a Bull Market for the RIA Industry

As good as the fourth quarter was for the S&P, it was even better for the RIA industry.  All classes of investment management firms bested the market, which was up 10% for the quarter.  Continued gains in the equity markets have allowed these firms to more than recover from last year’s correction, and many of these businesses are now trading at or near all-time highs.
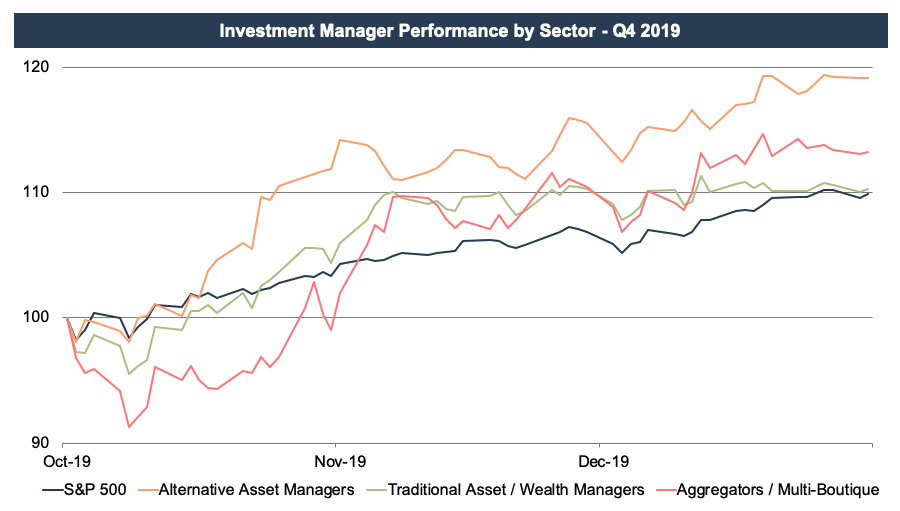
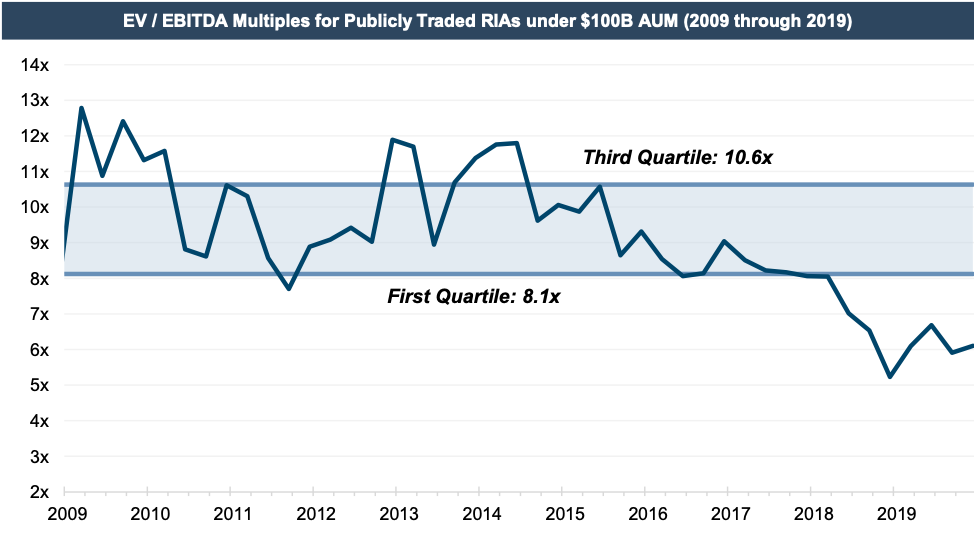
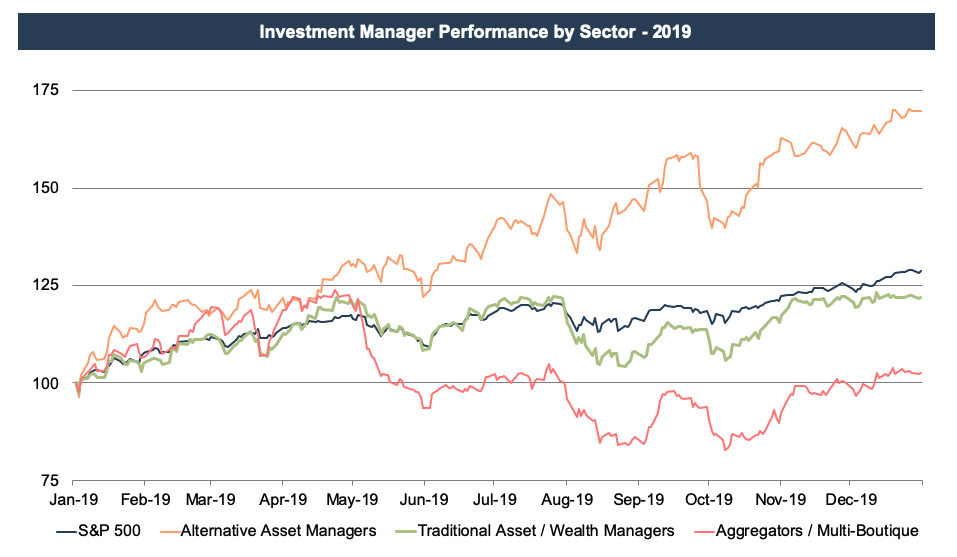
Despite these gains, the asset management industry is facing numerous headwinds, chief among them being the ongoing pressure for lower fees.  Alt managers, on the other hand, are perhaps more insulated from fee pressure due to the lack of passive alternatives to drive fees down. These headwinds have contributed to a decline in EBITDA multiples for traditional asset managers over the last few years despite the recent uptick in stock price performance.  As shown below, EBITDA multiples for these businesses remain well below historical norms, although they have recovered from their low point in December of 2018. Expanding the performance chart over the last year reveals an upward trend in pricing for most classes of RIAs.  Over this longer timeframe, alt managers are still the strongest category, although performance has been volatile.  Other pure play managers have generally moved in lockstep with the broader market while the aggregators lagged with AMG and FOCS’s performance. The relative underperformance of the aggregator and multi-boutique index may come as a surprise given all the press about consolidation in the industry and headline deals for privately held aggregators.  Over the last year, there have been two significant deals for privately-held wealth management aggregators: United Capital was bought by Goldman Sachs for $750 million, and Mercer Advisors’ PE backers sold a significant interest to a new PE firm, Oak Hill Capital Management.  Both the United Capital and Mercer Advisors deals reportedly occurred at high-teens multiples of adjusted EBITDA.
Implications for Your RIA

With EBITDA multiples for publicly-traded asset managers still well below historical norms, it appears the public markets are pricing in many of the headwinds the industry faces.  It is reasonable to assume that the same trend will have some impact on the pricing of privately-held asset managers as well.

But the public markets are just one reference point that informs the valuation of privately-held RIAs, and developments in the public markets may not directly translate to privately-held RIAs.  Depending on the growth and risk prospects of a particular closely-held RIA relative to publicly-traded asset and wealth managers, the privately-held RIA can warrant a much higher, or much lower, multiple.

Improving Outlook

The outlook for RIAs depends on a number of factors.  Investor demand for a particular manager’s asset class, fee pressure, rising costs, and regulatory overhang can all impact RIA valuations to varying extents.  The one commonality, though, is that RIAs are all impacted by the market.  Their product is, after all, the market.

The impact of market movements varies by sector, however.  Alternative asset managers tend to be more idiosyncratic but are still influenced by investor sentiment regarding their hard-to-value assets.  Wealth manager valuations are tied to the demand from consolidators while traditional asset managers are more vulnerable to trends in asset flows and fee pressure.  Aggregators and multi-boutiques are in the business of buying RIAs, and their success depends on their ability to string together deals at attractive valuations with cheap financing.

On balance, the outlook for RIAs appears to have improved since the significant market drop in December 2018.  Since then, industry multiples have rebounded somewhat, and the broader market has recovered its losses and then some—which should have a positive impact on future RIA revenues and earnings.

More attractive valuations could entice more M&A, coming off the heels of a record year in asset manager deal making.  We’ll keep an eye on all of it during what will likely be a very interesting year for RIA valuations.
Continue Reading

Eagle Ford – 2017/2018 Acquisition & Divestiture Commentary (1)
Eagle Ford – 2017/2018 Acquisition & Divestiture Commentary
Transaction activity in the Eagle Ford Shale has been fairly steady over the past 12 months, with the majority of transactions in the $100-300 million range.  The seller’s rationale has most often been about balance sheet management and re-allocation to other plays, usually the Permian Basin.  However, the Eagle Ford area has some quality economics of its own, which has been attractive to buyers.  Many argue it has the best shale production economics in the U.S. next to the Permian Basin.  These differing strategy based swaps have been at the heart of transaction flow.  This has also led to consideration that Devon may sell its Eagle Ford division in search of returns elsewhere.  The chart below, drawn from Mercer Capital’s newsletter, shows some details in regards to the transactions including some comparative valuation metrics.Magnolia – Blank Check Company forms a New South Texas ProducerThe largest transaction in the past year was the recent announcement of a special purpose acquisition entity (“SPAC”) coming to an agreement with certain Enervest controlled funds.  The result of the merger is the creation of a pure play Eagle Ford and Austin Chalk company with 360,000 net acres in South Texas.   The majority of that acreage is in what is known as the Giddings field which is an oil play in the Austin Chalk (mostly held by production).Break-evens are claimed to be in the low $30’s per barrel with one year (or less) paybacks in Karnes and Giddings field.  Magnolia1 is led by a former Occidental Petroleum executive, Steve Chazen, who has both short and long-term optimism for the opportunity.  Estimated EBITDA for 2018 is projected at $513 million including approximately $240 million of cash flow after capital expenditures.Highest and Best EconomicsDenver-based Sundance Energy Australia Ltd. struck a deal with Pioneer Natural Resource Co. to buy almost 22,000 acres and 1,800 boe/d of production in the Eagle Ford Shale, bolting on to an existing leasehold in South Texas.The pure-play Eagle Ford player agreed to pay $221.5 million for the leasehold, which runs through McMullen, Atascosa, LaSalle and Live Oak counties. The transaction would give Sundance 56,600 total acres in the play, with an inventory of 716 gross undrilled locations.Meanwhile, Pioneer was exiting to focus on the Permian Basin.  Pioneer announced in February it would put most of its resources going forward into the Permian and planned to sell nearly all “non-Permian” projects, including in the Eagle Ford, Raton Basin, and West Texas Panhandle.  The table below demonstrates why its desire to focus on the Permian was warranted.  However, one thing to note is that purchasing acreage in the Permian is much more expensive than the Eagle Ford, so drilling most likely needs to be based on existing acreage positions. Overall, the Eagle Ford’s economics are improving (Venado – a KKR backed Austin firm, made a $765 million purchase from Cabot that was based on this optimism). About 61,500 net acres of the Venado position, which is located primarily in Frio and Atascosa counties in South Texas, is operated and about 9,400 net acres are non-operated. Production from the properties during third-quarter 2017 was 15,656 barrels of oil equivalent per day. An interesting discussion on this acquisition can be found in this video: ?? Have a great week! Endnote1 In case one was wondering - Chip and Joanna Gaines are not involved.
Bankruptcy: An Overview Part 3 (1)
Bankruptcy: An Overview Part 3
From January through May of this year, 39 E&P companies and 31 oilfield services companies had to file for bankruptcy. This post is the last in a series of three aimed at helping those companies, and any others who may face bankruptcy in the future, to understand the valuation-related aspects of Chapter 11 restructuring. In the first post we highlighted two reorganization requirements tied to valuation. First, the plan should demonstrate that the economic outcomes for the consenting stakeholders are superior under the Chapter 11 proceeding compared to a Chapter 7 proceeding. Second, upon confirmation by the bankruptcy court, the plan must not be likely to result in liquidation or further reorganization. In the second post we explored in depth the consequences of the first requirement. Here we examine the importance of the second requirement.Cash-Flow TestFor a company that has followed the steps explained in the previous post, this second requirement represents the last valuation hurdle to successfully emerging from Chapter 11 restructuring. Even if a company shows that the restructuring plan will benefit stakeholders more than liquidation will, the court will still reject the plan if it is likely to lead to liquidation or further restructuring in the foreseeable future. To satisfy the court, a cash-flow test is used to analyze whether the restructured company would generate enough cash to consistently pay its debts. This cash-flow test can be broken into three parts.The first step in conducting the cash-flow test is to identify the cash-flows that the restructured company will generate. These cash-flows are available to service all the obligations of the emerging entity. Remember the discussion in the second post—a stream of cash-flows is developed using the DCF method in order to determine the reorganization value. Thus, in practice, establishing the appropriate stream of cash-flows for the cash-flow test is often a straightforward matter of using these projected cash-flows in the new model.Once the fundamental cash-flow projections are incorporated, analysts then model the negotiated or litigated terms attributable to the creditors of the emerging entity. This involves projecting interest and principal payments to the creditors, including any amounts due to providers of short term, working capital facilities. These are the payments for each period that the cash-flow generated up to that point must be able to cover in order for the company to avoid another bankruptcy.The cash-flows of the company will not be used only to pay debts, and so the third and final step in the cash-flow test is documenting the impact of the net cash-flows on the entire balance sheet of the emerging entity. This entails modeling changes in the company’s asset base as portions of the expected cash-flows are invested in working capital and capital equipment; and modeling changes in the debt obligations of and equity interests in the company as the remaining cash-flows are disbursed to the capital providers. A reorganization plan is generally considered viable if such a detailed cash-flow model indicates solvent operations for the foreseeable future.ConclusionAlthough the Chapter 11 process can seem like no more than a burden, a rigorous assessment of cash-flows and a company’s capital structure can help the company as it tries to develop a plan for years of future success. We hope that these past three posts explaining the key valuation-related steps of a Chapter 11 restructuring help managers realize this potential.However, we also understand that executives of oil and gas companies going through a Chapter 11 restructuring process need to juggle an extraordinary set of additional responsibilities—evaluating alternate strategies, implementing new and difficult business plans, and negotiating with various stakeholders. Given executives’ multitude of other responsibilities, they often decide that it is best to seek help from outside, third party specialists. Valuation specialists can relieve some of the burden from executives by developing the valuation and financial analysis necessary to satisfy the requirements for a reorganization plan to be confirmed by a bankruptcy court. Specialists can also provide useful advice and perspective during the negotiation of the reorganization plan to help the company emerge with the best chance of success. With years of experience in both oil and gas, and in bankruptcy, at Mercer Capital, we are well positioned to help in both of these roles. For a confidential conversation about bankruptcy proceedings and how we can help, please contact a Mercer Capital professional.
Does AI Spending Increase an RIA’s Value-or Just Reduce Its EBITDA?
Does AI Spending Increase an RIA’s Value - or Just Reduce Its EBITDA?
AI investment can create value for RIAs by improving capacity, growth, efficiency, and risk management, but the benefits must ultimately translate into stronger cash flow or reduced risk. Recurring AI costs generally remain operating expenses, making measurable adoption and returns critical to valuation.

Cart

Your cart is empty